The Global Urban Air Mobility Market — Why This Market Matters and Where It Is Heading
The Global Urban Air Mobility Market was valued at USD 10.2 billion in 2024 and is projected to reach USD 98.6 billion by 2035, expanding at a compound annual growth rate of 22.6% over the forecast period. This extraordinary growth trajectory places UAM among the most consequential technology-driven market formations of the current decade, comparable in structural transformation to the early commercial internet or the initial scaling of commercial solar energy. The market encompasses the full ecosystem of vehicles, infrastructure, software, and services required to make routine, safe, low-altitude urban flight a commercially viable transportation mode for passengers, cargo, and specialised missions in cities worldwide.
Urban Air Mobility addresses a problem that has resisted solution through ground-based transport for decades: the chronic congestion of urban road networks. The Texas A&M Transportation Institute estimates that urban congestion costs the United States economy alone more than USD 87 billion annually in lost productivity and excess fuel consumption. Globally, the burden across G20 metropolitan economies is estimated to exceed USD 1 trillion per year. UAM offers an entirely new dimension of urban transit, operating in previously unused low-altitude airspace, requiring no new road or rail infrastructure corridors, and delivering point-to-point journey times that are fundamentally unachievable through ground-based alternatives. The commercial problem it solves is therefore not merely convenience but the direct mitigation of a measurable and growing economic drag on urban productivity.
The market has been shaped over the past five years by three converging forces. First, battery energy density improvements have advanced sufficiently to make battery-electric propulsion viable for short-range urban missions, crossing the critical threshold of approximately 250 Wh/kg for commercial eVTOL applications. Second, regulatory frameworks that were conceptual five years ago have now advanced substantially, with the FAA completing its powered-lift certification framework in 2023 and EASA progressing its Special Condition for VTOL aircraft through active type certificate applications. Third, institutional capital has validated the sector at scale, with cumulative investment in UAM OEMs and infrastructure exceeding USD 15 billion globally as of end-2024.

The forecast period from 2024 to 2035 is particularly consequential because it encompasses the transition from demonstration and pre-commercial activity to genuine revenue-generating commercial operations at scale. Early commercial air taxi services are expected to commence in select North American and European city-pairs by 2026 to 2027, with broader network densification following through 2030 as vertiport infrastructure scales and autonomous operations certification unlocks operational economics that do not depend on pilot labour costs. The market will therefore progress through at least two distinct commercial phases within the forecast window: a high-cost premium service phase from 2025 to 2030, followed by a mass-market democratisation phase enabled by autonomy and manufacturing scale efficiencies from 2030 to 2035.
The geopolitical and macroeconomic context adds further dimensionality to market dynamics. Post-pandemic urban mobility patterns have shifted permanently, with hybrid working arrangements reducing peak-hour ground transit demand while increasing demand for flexible, on-demand mobility solutions that fit non-standard commute patterns. Supply chain disruptions exposed during 2020 to 2022 have motivated UAM OEMs to localise battery cell sourcing and advanced composite manufacturing, reshaping supplier strategies particularly in North America and the European Union. The US Inflation Reduction Act’s advanced manufacturing production credits have provided additional support to domestic eVTOL component manufacturers, while the EU’s Fit for 55 climate programme has elevated UAM within regional green transport planning frameworks.
Key Trends Actively Reshaping the Urban Air Mobility Market Landscape
Progressive FAA and EASA Certification Is the Market’s Single Most Critical Enabler. The completion of certification frameworks is not merely a regulatory milestone but the commercial trigger for the entire UAM ecosystem. The FAA’s issuance of its powered-lift final rule in October 2023 established the definitive pathway for eVTOL type certificates in the United States, removing the principal uncertainty that had constrained airline commitments and infrastructure investment. EASA’s parallel certification of Volocopter’s VoloCity for commercial operations in European airspace advances the same unlocking dynamic in the largest unified aviation market outside the US. The commercial consequence is that OEMs with advanced certification programmes, specifically Joby Aviation, Archer Aviation, and Wisk Aero in the US and Vertical Aerospace in Europe, have moved from speculative to credible commercial actors, enabling airlines to activate their pre-order agreements and infrastructure developers to commit capital.
Hydrogen Fuel Cell Propulsion Is Emerging as the Long-Range UAM Technology Disruptor. While battery-electric eVTOLs dominate the current development landscape, hydrogen fuel cell propulsion is advancing rapidly as the technology solution for medium-range urban and inter-city missions beyond the 60 to 80 kilometre range ceiling of current lithium-ion platforms. ZeroAvia’s HyFlyer programme achieved a 19-seat hydrogen-electric commercial aircraft flight in January 2023, and multiple eVTOL OEMs have publicly disclosed hydrogen propulsion development tracks for second-generation platforms targeted at 2030 commercial entry. Governments are accelerating this trend through hydrogen aviation investment, with the European Clean Hydrogen Alliance committing EUR 2 billion to aviation hydrogen applications through 2030. The commercial consequence of successful hydrogen UAM commercialisation post-2030 would be a step-change expansion of addressable market geographies and mission profiles, representing a material upside driver for the 2031 to 2035 portion of the forecast period.
Vertiport Infrastructure Is Emerging as the Critical Bottleneck and Investment Opportunity. The physical infrastructure required to support commercial UAM networks — vertiports with charging capability, passenger processing, and air traffic management connectivity — is increasingly recognised as both the sector’s most capital-intensive requirement and its most durable competitive moat. Skyports, Urban-Air Port, Ferrovial, and VINCI Airports have initiated vertiport development programmes in the UK, Dubai, Singapore, and Miami respectively. The UK Government’s Future Flight Challenge programme committed GBP 125 million to advanced air mobility infrastructure in 2023, including vertiport pilot sites at Coventry and Dublin. Infrastructure investment decisions made in 2024 to 2027 will determine which cities capture first-mover UAM network advantages, with the commercial consequence that real estate, construction, and airport management companies are rapidly repositioning themselves as structural participants in the UAM value chain.
Autonomous UAM Systems Are Progressing Faster Than Market Consensus Anticipated. Full autonomy — eVTOL operations without a pilot or remote operator — is advancing through regulatory and technological pathways simultaneously. Wisk Aero, backed by Boeing, has built its entire certification strategy around a fully autonomous platform, receiving BVLOS operational approval in New Zealand in 2024 as a precursor to FAA engagement. EHang Holdings received the world’s first type certificate for a pilotless autonomous aerial vehicle from China’s CAAC in October 2023, establishing a precedent that autonomous certification is achievable within current regulatory frameworks. The commercial significance is substantial: autonomous operations eliminate pilot labour costs that account for approximately 40 to 60 per cent of operating expenses for piloted air taxi services, transforming UAM unit economics and making the mass-market pricing scenarios modelled for 2030 to 2035 credibly achievable.
What Is Driving Growth and What Is Holding It Back — Drivers, Restraints and Opportunities
Market Drivers
FAA and EASA Powered-Lift Certification Frameworks Are Removing the Market’s Principal Commercial Barrier. The completion and active implementation of regulatory certification pathways by the FAA and EASA in 2023 and 2024 has transformed the UAM investment and commitment landscape from speculative to executable. Airlines, airports, and infrastructure investors can now make capital allocation decisions against defined regulatory timelines, enabling the multi-year supply chain and vertiport investments that commercial UAM networks require. The FAA’s Powered Lift Aircraft Aviation Rulemaking Committee delivered its final recommendations in 2023, and type certificate applications are actively progressing for multiple OEMs within this framework.
Urban Road Congestion Costs Exceeding USD 1 Trillion Annually Are Creating Inescapable Commercial Demand. The economic burden of ground-level urban congestion represents an unsolved and worsening problem across the world’s most economically productive metropolitan centres. McKinsey Global Institute analysis estimates that urban traffic congestion costs G20 economies more than 2% of GDP annually, a figure that compounds as urban populations grow. UAM’s ability to bypass ground infrastructure entirely by utilising low-altitude airspace positions it as a genuine structural alternative to road expansion for premium inter-district mobility, creating commercial demand that is demand-pull rather than technology-push in its fundamental driver dynamic.
Battery Technology Advances Are Extending eVTOL Range and Payload Viability with Each Product Generation. Lithium-ion battery energy density has improved from approximately 200 Wh/kg in 2018 to 280 to 300 Wh/kg in current commercial eVTOL platform designs, with solid-state battery development programmes at Samsung SDI, QuantumScape, and Solid Power targeting 400-plus Wh/kg by 2028. Each energy density improvement extends the commercially viable range of battery-electric eVTOL platforms, expanding the addressable route network and the proportion of urban mobility missions that UAM can serve economically. The next generation of commercially launching eVTOLs, expected in the 2027 to 2029 timeframe, will incorporate materially improved battery technology compared to current first-generation platforms.
Airline Pre-Order Commitments Representing Over 3,000 Aircraft Are Anchoring the Commercial Business Case. Strategic pre-purchase agreements from United Airlines (with Archer Aviation), American Airlines (with Vertical Aerospace), and Japan Airlines (with Joby Aviation) collectively represent commitments to over 3,000 eVTOL aircraft worth in excess of USD 7 billion at list prices. These commitments perform multiple market functions simultaneously: they validate commercial demand from operators with established passenger relationships, they provide OEMs with revenue visibility to secure financing for manufacturing scale-up, and they signal to vertiport developers and city planners that commercial operations are commercially committed rather than aspirational.
Smart City and Green Transport Policies Are Creating Government-Backed Market Acceleration. Governments across North America, Europe, Asia, and the Middle East are incorporating UAM into national transport and Sustainability Strategies, providing both direct funding support and enabling regulatory prioritisation. The US Department of Transportation’s Urban Air Mobility Grand Challenge programme, the European Union’s Urban Air Mobility Initiative under the SESAR Joint Undertaking, and Singapore’s Civil Aviation Authority UAM advisory framework all represent institutional commitments that reduce commercial risk for private investors and accelerate the regulatory engagement timelines that are critical path for market entry.
Autonomous Flight Software Maturation Is Transforming UAM Unit Economics Toward Mass-Market Viability. The progressive commercialisation of autonomous flight management systems by companies including Skyryse, Reliable Robotics, and in-house development programmes at Wisk Aero and EHang is systematically reducing the operating cost structure of UAM services. Autonomous operations, once certified, eliminate the primary variable cost of commercial aviation — pilot compensation — which currently constitutes 40 to 60 per cent of air taxi operating expenses. The transition to autonomous operations by 2030 to 2032 is the single most consequential unit economics event in the UAM forecast period, enabling ticket price reductions that expand the addressable passenger market by an estimated factor of 8 to 12 relative to piloted premium pricing.
Cargo and Medical UAM Applications Are Providing Near-Term Revenue While Passenger Certification Advances. Cargo delivery and emergency medical service applications of UAM platforms face materially simpler regulatory environments than passenger air taxi operations, enabling earlier commercial revenue generation. Companies including Beta Technologies (UPS partnership), Natilus, and Reliable Robotics have established cargo UAM contracts that generate real operating revenue and accumulate safety data that supports the broader regulatory case for UAM safety. Medical emergency transport applications have received specific regulatory accommodation in multiple US state programmes and in Norway, where electric aerial ambulance services are advancing under government healthcare procurement frameworks.
Market Restraints
Regulatory Certification Timelines of 6 to 10 Years Remain the Dominant Commercialisation Constraint. Despite the significant progress made by the FAA and EASA in establishing powered-lift certification frameworks, the practical timeline from a completed type certificate application to revenue-generating commercial operations remains 6 to 10 years for novel aircraft categories. This extended timeline reflects the inherently risk-averse nature of aviation safety regulation, the requirement for extensive flight test programmes, and the absence of historical safety datasets for eVTOL platforms that regulators rely upon when establishing certification bases. OEMs that entered type certification processes in 2020 to 2022 are therefore not expected to achieve full commercial certification before 2026 to 2028, and delays within individual programmes have been commonplace.
Vertiport Infrastructure Capital Requirements Are Creating Significant Network Scaling Barriers. The capital investment required to develop, equip, and operate a commercial vertiport facility ranges from USD 3 million for a basic rooftop facility to USD 20 million or more for a full-service ground-level vertiport with multiple landing pads, passenger processing, fast-charging infrastructure, and maintenance capability. Scaling a UAM network to meaningful commercial density requires hundreds of such facilities within a single metropolitan market. The aggregate capital requirement for network-level vertiport infrastructure in a single major city such as Los Angeles, London, or Singapore is estimated at USD 500 million to USD 2 billion, representing a financing challenge that requires institutional real estate capital, government co-investment, or public-private partnership structures that take time to negotiate and execute.
Public Acceptance and Community Opposition to Low-Altitude Noise and Visual Intrusion Represents a Social Licence Risk. Urban residents consistently demonstrate sensitivity to noise and visual disruption from low-altitude aircraft operations, even when those aircraft are significantly quieter than conventional helicopters. Research conducted in association with European UAM regulatory consultations found that community acceptance is contingent on acoustic performance thresholds that current first-generation eVTOL platforms are approaching but have not universally achieved. Organised community opposition to vertiport siting and operational route planning has delayed project timelines in multiple markets, and the commercial consequence of sustained community resistance could include route restrictions, operating hour limitations, and vertiport location constraints that materially reduce network density and commercial viability.
Battery Energy Density Limitations Continue to Constrain Range and Payload for Commercial eVTOL Operations. Despite consistent improvement in lithium-ion battery technology, current energy density levels limit battery-electric eVTOL platforms to commercially viable ranges of 50 to 100 kilometres on a single charge under operational payload conditions. This range constraint limits the geographic scope of commercial UAM networks and excludes inter-city missions that represent the highest revenue-per-flight potential. Recharging times of 20 to 45 minutes for fast-charging current-generation batteries also reduce aircraft utilisation rates relative to conventional aviation, constraining network throughput at shared vertiport infrastructure. Until solid-state or next-generation battery technologies achieve commercial deployment, range and turnaround time limitations will continue to define addressable market boundaries.
Skilled Pilot and Maintenance Workforce Shortages Represent a Near-Term Operational Bottleneck. The global aviation industry is experiencing a structural pilot shortage estimated at 80,000 commercial pilots by 2032 according to Boeing’s Pilot and Technician Outlook. The introduction of a new powered-lift aircraft category requiring specialist type-rated pilots adds competitive pressure to an already constrained labour pool. eVTOL OEMs must develop type-specific training programmes, simulators, and qualification pathways from scratch, adding time and cost to pre-commercial operations. Maintenance workforce development presents parallel challenges, as eVTOL platforms require technicians skilled in electric propulsion, high-voltage battery systems, and software-defined avionics — competencies that are scarce within traditional aviation maintenance organisations.
Market Opportunities
Hydrogen Fuel Cell UAM for Medium-Range Missions Represents a Structural Market Expansion Opportunity Beyond 2030. The limitations of battery-electric propulsion for missions beyond 80 to 100 kilometres create a defined technology gap that hydrogen fuel cell propulsion is positioned to address. OEMs and investors who develop credible hydrogen UAM platforms for the 2030 to 2035 commercial window will access a mission segment — regional inter-city UAM — that is currently not addressable by any certified platform. The market gap is estimated to represent an incremental USD 15 to 25 billion in addressable market value within the forecast period, positioning it as one of the highest-value strategic opportunities for second-generation UAM platform development.
Vertiport Infrastructure Development and Operation Offers Durable, Capital-Efficient Investment Returns for Infrastructure Capital. The structural requirement for hundreds of vertiport facilities per metropolitan market creates a large-scale infrastructure investment opportunity with characteristics — predictable utilisation, long asset lives, regulated access pricing, and first-mover location advantages — that are highly attractive to infrastructure funds, pension capital, and real estate investment trusts. Early-mover vertiport developers are accumulating siting agreements with airports, railway stations, and commercial real estate owners that will be difficult for later entrants to replicate, creating durable competitive advantages in the infrastructure layer of the UAM value chain.
Cargo and Logistics UAM Represents the Near-Term Commercial Entry Point with Lower Regulatory Barriers than Passenger Operations. Urban cargo delivery, last-mile medical supply delivery, and inter-facility logistics represent UAM applications that face significantly lighter regulatory requirements than passenger operations, enabling commercial revenue generation 2 to 4 years earlier than air taxi services. E-Commerce logistics operators, healthcare systems, and defence procurement agencies represent identified buyers with operational budgets and defined use cases. Companies that establish commercial cargo UAM operations in 2025 to 2028 will build the safety records, operational learnings, and regulatory relationships that provide structural advantages when transitioning to higher-margin passenger operations in subsequent years.
- ■ By Product Type
- ■ By Application
- ■ By End-User
- ■ By Region
| Year | 1st QTR | 2nd QTR | 3rd QTR | 4th QTR |
|---|---|---|---|---|
| 2025 | XX Mn/Bn | XX Mn/Bn | XX Mn/Bn | XX Mn/Bn |
| 2024 | XX Mn/Bn | XX Mn/Bn | XX Mn/Bn | XX Mn/Bn |
| 2023 | XX Mn/Bn | XX Mn/Bn | XX Mn/Bn | XX Mn/Bn |
| 2026 | XX Mn/Bn | 2031 | XX Mn/Bn |
| 2027 | XX Mn/Bn | 2032 | XX Mn/Bn |
| 2028 | XX Mn/Bn | 2033 | XX Mn/Bn |
| 2029 | XX Mn/Bn | 2034 | XX Mn/Bn |
| 2030 | XX Mn/Bn | 2035 | XX Mn/Bn |
How the Urban Air Mobility Market Divides — A Full Segmentation Analysis
The Urban Air Mobility Market is structured across five primary segmentation dimensions, each revealing distinct commercial dynamics, technology trajectories, and near-term opportunity concentrations. Understanding the intersection of these dimensions is essential for identifying where capital deployment, technology development, and route network investment will generate the highest returns within the forecast period.
By Vehicle Type — eVTOLs Lead With 42% Share While Hybrid VTOL Offers the Strongest Near-Term Growth Bridge Analysis
By Vehicle Type — eVTOLs Lead With 42% Share While Hybrid VTOL Offers the Strongest Near-Term Growth Bridge
Electric Vertical Take-Off and Landing vehicles command the dominant position in the vehicle type segmentation at approximately 42% of market revenue in 2024, driven by their superior alignment with urban operations requirements: near-zero direct emissions, significantly reduced acoustic signature relative to conventional rotorcraft, mechanical simplicity through distributed electric propulsion, and eligibility for the most favourable regulatory certification pathways currently being developed. Conventional VTOL platforms, primarily existing helicopter formats adapted for commercial mobility services, retain approximately 28% of market share and continue to serve premium and emergency missions where range and payload requirements exceed current eVTOL capabilities. Hybrid VTOL platforms, incorporating both electric and combustion propulsion elements, represent the fastest-growing transitional segment at a projected CAGR of 20.7%, serving as the bridge technology for operators requiring extended range without sacrificing the operational flexibility of vertical lift.
By Autonomy Level Analysis
By Autonomy Level — Piloted Operations Dominate Today While Full Autonomy Represents the Highest-CAGR Sub-Segment at 32.5%
Piloted crewed eVTOL operations represent the majority of commercial activity in 2024, accounting for approximately 55% of segment revenue, because regulatory certification for piloted platforms is achievable faster than for autonomous systems under current frameworks. Remotely piloted operations hold 30% of segment share, predominantly in cargo and surveillance applications where BVLOS operations are progressing through regulatory approval in multiple jurisdictions. Fully autonomous operations, while representing only 15% of current segment revenue, carry the highest projected CAGR of any UAM sub-segment at 32.5%, reflecting the transformative unit economics improvement that autonomous certification enables and the advanced certification progress being made by Wisk Aero and EHang Holdings in their respective markets.
By Application — Passenger Air Taxi Leads at 38% While Cargo UAM Delivers the Fastest Growth at 28.1% CAGR Analysis
By Application — Passenger Air Taxi Leads at 38% While Cargo UAM Delivers the Fastest Growth at 28.1% CAGR
Passenger Air Taxi Services anchor the application segmentation with 38% revenue share, driven by the highest per-flight revenue potential and the largest concentration of OEM, airline, and infrastructure investment. Commercial air taxi operations are being built around airport connectivity, premium urban commuter routes, and event-based mobility, with early commercial launches targeting the 2026 to 2027 window in Los Angeles, Dallas, Miami, and Singapore. Cargo and Logistics Delivery represents the fastest-growing application segment with a projected CAGR of 28.1%, underpinned by e-commerce volume growth, healthcare supply chain modernisation, and significantly faster regulatory approvals for unmanned cargo platforms. Emergency Medical Services at 18% share represent a strategically important application with strong government support and a direct public health value proposition that generates regulatory goodwill benefiting the broader UAM ecosystem.
By Propulsion — Battery Electric Leads at 48% While Hydrogen Fuel Cell Emerges as the Long-Term Disruptive Sub-Segment Analysis
By Propulsion — Battery Electric Leads at 48% While Hydrogen Fuel Cell Emerges as the Long-Term Disruptive Sub-Segment
Battery-electric propulsion systems command 48% of propulsion segment revenue in 2024, reflecting the current technology mainstream of commercial eVTOL development. Hybrid electric systems at 32% serve the range-extension market segment. Hydrogen fuel cell propulsion holds 12% of segment share in 2024 but projects the highest sub-segment CAGR of 34.2%, reflecting accelerating investment in hydrogen aviation propulsion, government hydrogen economy commitments, and the structural advantage of hydrogen energy density (approximately 33 kWh/kg versus 0.3 kWh/kg for lithium-ion batteries) for longer-range UAM missions. The hydrogen sub-segment CAGR reflects a combination of low current base and genuine technology inflection expected in the late 2020s.
By Distribution Channel — OEM Direct Sales Lead While MaaS Platforms Represent the Fastest Commercial Channel Growth Analysis
By Distribution Channel — OEM Direct Sales Lead While MaaS Platforms Represent the Fastest Commercial Channel Growth
OEM direct sales account for 52% of channel revenue, reflecting the early-stage commercial structure in which aircraft manufacturer relationships with airline operators and government agencies constitute the primary transaction mechanism. Mobility-as-a-Service platforms, including Blade Air Mobility’s aggregator model and emerging digital booking platforms from Volocopter and Joby Aviation, represent 31% of channel revenue but project the highest CAGR of 30.4%, as MaaS aggregation models are expected to drive passenger demand democratisation in the 2028 to 2035 period. Government and defence procurement at 17% represents a stable, long-term channel with high per-unit contract values but extended procurement cycles.
The segmentation analysis indicates that the highest near-term commercial opportunity concentration sits at the intersection of multi-passenger eVTOL platforms (4 to 6 seats), passenger air taxi applications, battery-electric propulsion, and MaaS channel distribution, targeting city-pair premium commuter routes in North America and Western Europe. Concurrently, cargo UAM via battery-electric remotely piloted platforms represents the highest-certainty near-term revenue opportunity for operators seeking earlier commercial traction with reduced regulatory complexity.
| Segment | Sub-Segment | 2024 Share | CAGR 2024–2035 |
| Vehicle Type
|
eVTOL | 42% | 24.1% |
| Conventional VTOL | 28% | 15.3% | |
| Hybrid VTOL | 18% | 20.7% | |
| Autonomy Level | Fully Autonomous | 15% | 32.5% |
| Application | Passenger Air Taxi | 38% | 26.3% |
| Cargo and Logistics | 25% | 28.1% | |
| Propulsion | Hydrogen Fuel Cell | 12% | 34.2% |
| Channel | MaaS Platforms | 31% | 30.4% |
Complete Market Segmentation — All Segments and Sub-Segments
| Segment Category | Sub-Segment | Market Share (2024) | Projected CAGR |
| By Vehicle Type | eVTOL (Electric Vertical Take-Off and Landing) | 42% | 24.1% |
| Conventional VTOL | 28% | 15.3% | |
| Hybrid VTOL | 18% | 20.7% | |
| Fixed-Wing Transitional | 12% | 18.4% | |
| By Autonomy Level | Piloted (Crewed) | 55% | 16.2% |
| Remotely Piloted | 30% | 23.8% | |
| Fully Autonomous | 15% | 32.5% | |
| By Application | Passenger Air Taxi Services | 38% | 26.3% |
| Cargo and Logistics Delivery | 25% | 28.1% | |
| Emergency Medical Services (EMS) | 18% | 22.9% | |
| Surveillance and Security | 12% | 19.4% | |
| Tourism and Leisure | 7% | 17.8% | |
| By Propulsion
|
Electric (Battery-Powered) | 48% | 25.6% |
| Hybrid Electric | 32% | 21.3% | |
| Hydrogen Fuel Cell | 12% | 34.2% | |
| Conventional Fuel | 8% | 10.1% | |
| By Platform
|
Single-Passenger Vehicles | 22% | 27.4% |
| Multi-Passenger Vehicles (4–6 Seats) | 44% | 23.9% | |
| Cargo-Only UAM Platforms | 34% | 29.1% | |
| By Distribution/Channel | OEM Direct Sales | 52% | 18.6% |
| Mobility-as-a-Service (MaaS) Platforms | 31% | 30.4% | |
| Government and Defence Procurement | 17% | 15.2% |
Where in the World the Urban Air Mobility Market Is Growing — A Regional Analysis Analysis
Share
Share
Share
Share
Share
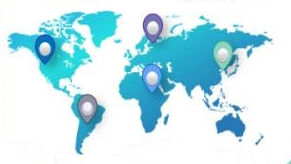
Where in the World the Urban Air Mobility Market Is Growing — A Regional Analysis
North America Commands the Largest Regional Share and Will Continue to Lead Through 2035 on the Strength of FAA Certification Progress and OEM Depth
North America accounted for approximately USD 3.9 billion of the Global UAM Market in 2024, representing the leading regional share of approximately 38%. The United States is the anchor of North American UAM activity, hosting the world’s most advanced eVTOL OEM ecosystem with Joby Aviation, Archer Aviation, Wisk Aero, Beta Technologies, and Blade Air Mobility all headquartered domestically. The FAA’s completion of its powered-lift certification framework in 2023 has provided a defined regulatory pathway that is enabling type certificate applications to advance with a degree of predictability previously absent from the US regulatory landscape. United Airlines’ partnership with Archer Aviation, representing an order for up to 100 Midnight aircraft for airport-to-city operations in key hubs, and American Airlines’ agreement with Vertical Aerospace for up to 250 VX4 aircraft represent institutional demand commitments that anchor the commercial business case for North American UAM network development. The US Department of Transportation’s AAM National Strategy commits federal support to UAM integration across all phases of commercial development. Canada is emerging as a secondary growth market, with Transport Canada advancing its own advanced air mobility regulatory framework and Montreal emerging as a pilot city for vertiport site development. The North American market is projected to maintain its leading regional position throughout the forecast period, with the regional CAGR estimated at 21.8%.
Asia Pacific Is the World’s Fastest Growing UAM Region, Powered by China’s Regulatory Leadership and India’s Urban Growth Imperative
The Asia Pacific region represents the fastest-growing UAM geography globally, projected to deliver the highest regional CAGR of approximately 26.3% over the 2024 to 2035 forecast period. The region accounted for approximately USD 2.8 billion of global UAM market revenue in 2024, representing approximately 27% of global share, and is expected to approach or exceed North America’s revenue share by the end of the forecast period. China is the defining force within Asia Pacific UAM, with EHang Holdings securing the world’s first CAAC type certificate for a fully autonomous aerial vehicle in October 2023, establishing China as the first nation to certify a commercially operable autonomous UAM platform. The CAAC’s proactive engagement with novel aircraft categories, supported by the Chinese government’s civil aviation development strategy for 2035, positions China to develop the world’s largest domestic UAM operational network over the forecast horizon.
India represents the region’s most consequential emerging market opportunity, driven by the combination of extreme urban congestion in tier-one cities including Mumbai, Delhi, and Bengaluru, rapidly rising urban middle-class incomes, and a government administration under the National Civil Aviation Policy (NCAP) framework that has explicitly identified urban air mobility as a strategic priority. The Civil Aviation Ministry’s drone policy evolution, progressing from Drone Rules 2021 through subsequent advanced air mobility consultations, is creating an enabling regulatory environment ahead of commercialisation timelines. Blade Air Mobility’s expansion into India through its Mumbai operations demonstrates that premium urban air mobility demand exists at existing price points within the current generation of rotorcraft operations. Japan and South Korea are contributing significant technology and investment to regional UAM development, with Supernal (Hyundai Motor Group) advancing the S-A2 eVTOL platform unveiled at CES 2024, and Japan Airlines’ partnership with Joby Aviation representing one of Asia’s largest committed airline UAM investments. Southeast Asia, particularly Singapore, is developing rapidly as both an operational testbed and a regulatory benchmark for the broader ASEAN region, with Singapore’s CAAS issuing advanced air mobility advisory frameworks and Skyports advancing vertiport planning at Changi Airport. Separate region-specific research studies covering Asia Pacific UAM markets are available from Vantage Market Research.
Europe Leverages Regulatory Alignment and Green Transport Mandates to Build a Coherent UAM Market Across the EU Member States
Europe accounted for approximately USD 2.1 billion of the Global UAM Market in 2024, representing approximately 21% of global revenue. The European market is defined by the highly coordinated regulatory approach of EASA, whose Special Condition for VTOL (SC-VTOL) framework provides a consistent certification basis across all 27 EU member states plus aligned non-EU markets including the UK and Switzerland. Germany and France are the leading country-level markets, with Volocopter’s VoloCity type certification engagement with EASA and Lilium’s re-emergence under new investor ownership in 2025 representing the most advanced German OEM developments. France is pursuing UAM integration as a component of its post-2024 Paris Olympics smart mobility legacy programme, with the French Civil Aviation Authority (DGAC) advancing vertiport siting frameworks for Paris and Lyon. The European Union’s Urban Air Mobility Initiative, operating under the SESAR Joint Undertaking, has committed EUR 300 million to UAM demonstrator programmes and air traffic management integration research, representing the world’s largest government-funded UAM research programme. The UK, operating independently post-Brexit through the Civil Aviation Authority, has maintained policy alignment with EASA on eVTOL certification while developing its own Future Flight Challenge programme, which has committed GBP 125 million to advanced air mobility including vertiport development at Coventry and Manchester. Separate region-specific research studies covering European UAM markets, including country-level analysis, are available from Vantage Market Research.
Latin America Emerges as a Nascent but Strategically Positioned UAM Market Led by Brazil’s Urban Aviation Ambitions
Latin America accounted for approximately USD 650 million of the Global UAM Market in 2024, representing approximately 6% of global revenue. The region’s market is at an earlier stage of development than North America, Europe, and Asia Pacific, but it is advancing rapidly from a low base, with a projected regional CAGR of approximately 24.1% through 2035. Brazil is the dominant Latin American UAM market, driven by the world-class aerospace manufacturing ecosystem centred on the Embraer Group and its NYSE-listed subsidiary Eve UAM, which is developing both eVTOL platforms and urban traffic management services as an integrated product offering. Sao Paulo and Rio de Janeiro represent natural early-market targets for UAM air taxi services, given their extreme road congestion, well-established helicopter commuter culture among premium users, and the density of potential air mobility demand corridors. Distribution infrastructure for UAM in Latin America presents challenges related to the concentration of aviation investment in a small number of major cities and the relative underdevelopment of regulatory frameworks outside Brazil. Vantage Market Research offers a separate region-specific study covering the Latin America UAM market in depth.
Middle East and Africa Are Establishing UAM Leadership Through Proactive Government Investment and World-Class Infrastructure Development
The Middle East and Africa region accounted for approximately USD 800 million of the Global UAM Market in 2024, representing approximately 8% of global revenue. The region punches significantly above its geographic market development weight, driven by proactive government investment in UAM infrastructure and regulatory enablement in the UAE and Saudi Arabia. The UAE’s Civil Aviation Authority has prioritised UAM commercialisation as a component of the Dubai 2040 Urban Master Plan, with the Roads and Transport Authority (RTA) of Dubai signing partnership agreements with Joby Aviation and Archer Aviation for commercial air taxi route planning and vertiport development. Saudi Arabia’s NEOM project, the USD 500 billion smart city development currently under construction, has incorporated UAM as a foundational element of its internal mobility infrastructure, representing one of the largest guaranteed government UAM procurement opportunities globally. Rising urban income levels across Gulf Cooperation Council countries, combined with tourism volume growth and the demonstrated willingness of GCC consumers to adopt premium mobility services, support robust near-term demand for commercial air taxi services at the pricing levels that first-generation UAM operations will require. Vantage Market Research offers a separate region-specific study covering the Middle East and Africa UAM market, including country-level analysis for UAE, Saudi Arabia, South Africa, and Egypt.
The Competitive Landscape — Who Leads, How They Compete and What Separates the Leaders
The Global Urban Air Mobility Market presents a competitive landscape that is simultaneously fragmented at the total company count level and concentrated at the level of commercially viable, certification-advanced platforms. More than 400 companies globally have disclosed eVTOL or UAM-related development programmes, but the field of credible near-term commercial contenders — companies with advanced type certificate applications, institutional airline partnerships, and committed manufacturing plans — numbers fewer than 15 globally. This bifurcated structure is characteristic of deep technology markets in their pre-commercialisation phase, where the transition from prototype to certified commercial product creates a dramatic attrition among early entrants and concentrates competitive outcomes among the best-capitalised and technically most advanced players.
Competitive strategy in the UAM market operates across four primary dimensions: regulatory advancement speed, manufacturing and supply chain commitment, airline and operator partnership depth, and infrastructure ecosystem development. Companies that compete on regulatory advancement speed, primarily Joby Aviation, Archer Aviation, and Wisk Aero in the US and Volocopter and Vertical Aerospace in Europe, are investing heavily in flight test programmes, FAA/EASA engagement, and pilot training development to achieve type certificates ahead of competitors. Manufacturing and supply chain commitment is the second strategic dimension, with Beta Technologies’ decision to develop its own manufacturing facility in Vermont and Archer Aviation’s agreement with Stellantis for manufacturing support representing meaningful differentiation from asset-light competitors who rely on contract manufacturing.
In May 2024, Joby Aviation and Toyota Motor Corporation deepened their manufacturing collaboration through a USD 500 million investment commitment from Toyota, giving Joby access to Toyota’s global manufacturing excellence methodologies and supply chain scale. In October 2024, Archer Aviation completed its first conforming Midnight aircraft and entered FAA flight test operations, representing the most advanced publicly documented US eVTOL certification milestone of the year. These two developments illustrate the pattern by which leading players are creating cumulative competitive advantages that compound progressively, making it increasingly difficult for later-stage competitors to catch up through capital infusion alone.
Company Profiles — Leading Urban Air Mobility Market Participants
Joby Aviation (USA) is the closest to FAA type certification of any US-based eVTOL OEM, having secured an FAA Part 135 Air Carrier Certificate in 2023 that allows it to operate air taxi services once its aircraft is type-certified. Backed by Toyota, Delta Air Lines, and United Airlines, Joby’s five-seat, 150-mile range eVTOL platform is designed for airport shuttle and intra-city premium mobility operations. In early 2025, Joby commenced conforming aircraft production at its Marina, California facility.
Archer Aviation (USA) has delivered its Midnight eVTOL aircraft to FAA flight testing and established a manufacturing partnership with Stellantis for vehicle production at scale. Its agreement with United Airlines for up to 100 Midnight aircraft for Newark-to-Manhattan routes represents one of the highest-profile commercial deployment commitments in the sector. Archer completed its first piloted Midnight flight in November 2023 and has since accumulated hundreds of test flight hours.
Lilium GmbH (Germany) pioneered the electric jet-powered eVTOL concept through its distributed electric jet propulsion system, offering superior cruise speed and noise performance compared to multirotor eVTOLs. After a restructuring process in late 2024, Lilium secured new investment backing and recommenced its certification programme in 2025, targeting EASA type certificate in the 2027 to 2028 timeframe.
Volocopter (Germany) operates the most extensive pre-commercial UAM demonstration programme of any European OEM, having conducted public demonstration flights at Singapore, Dubai, Helsinki, and Paris. Its VoloCity two-seat air taxi is in active EASA type certification engagement, and its partnership with SATS Ltd. is developing operational vertiport infrastructure in Singapore ahead of commercial launch.
Wisk Aero (USA, Boeing-backed) is the industry’s leading autonomous eVTOL developer, with its Generation 6 aircraft in active FAA certification engagement and a unique regulatory strategy built around demonstrating autonomous flight safety rather than piloted operations. Its 2024 BVLOS operational approval in New Zealand marks a significant milestone in international autonomous UAM regulatory acceptance.
EHang Holdings (China) achieved a historic global first in October 2023 by receiving the CAAC type certificate for its EH216-S pilotless autonomous aerial vehicle, making it the only company in the world with a certified commercial autonomous UAM platform. EHang is developing commercial operations across China and internationally, with government-backed deployment programmes in multiple Chinese provincial markets.
Vertical Aerospace (UK) is developing the VX4 eVTOL aircraft with pre-orders from American Airlines, Virgin Atlantic, and Japan Airlines totalling up to 1,500 aircraft. Headquartered in Bristol, Vertical is leveraging the UK’s Future Flight Challenge programme and deep aerospace engineering talent base from the Bristol and GKN Aerospace supply chain ecosystem.
Beta Technologies (USA) has differentiated itself through a dual strategy of eVTOL platform development (ALIA) and proprietary fast-charging infrastructure development, with over 100 charging sites deployed or committed across the United States. Its cargo partnership with UPS provides early commercial revenue and safety data accumulation. Beta’s investor base includes Amazon’s climate fund and United Airlines Ventures.
Supernal — Hyundai Motor Group (USA / South Korea) unveiled its S-A2 eVTOL concept at CES 2024, showcasing an advanced 4-passenger platform designed for the 2028 commercial entry timeframe. Hyundai’s USD 7.4 billion advanced air mobility investment commitment, announced in 2022, positions Supernal as one of the best-capitalised OEMs in the sector with deep automotive manufacturing expertise applicable to eVTOL production scale-up.
Eve UAM — Embraer (Brazil / USA) is listed on the NYSE and benefits from its parent company Embraer’s 50-year commercial aviation manufacturing heritage and global MRO network. Eve’s strategy uniquely combines eVTOL platform development with urban air traffic management services, providing a vertically integrated offering to city and airline operator customers. Eve has signed MoUs with over 30 city and operator partners globally.
Airbus UpNext (France / EU) is advancing the CityAirbus NextGen, a four-seat eVTOL with a 80 km range, through EASA type certification. Airbus brings unmatched regulatory relationships, global manufacturing footprint, and established airline customer relationships to the UAM sector, positioning CityAirbus NextGen as the most credible European OEM platform for commercial airline operator procurement.
Boeing NeXt (USA) is Boeing’s advanced mobility division, pursuing autonomous cargo and passenger UAM platforms under its Passenger Air Vehicle (PAV) and Cargo Air Vehicle (CAV) programmes. Boeing’s strategic objective is to develop the autonomous systems and manufacturing knowledge base to remain competitive in the UAM market as it transitions from piloted to autonomous operations over the forecast period.
Blade Air Mobility (USA) operates as the sector’s leading MaaS aggregator, providing helicopter and eVTOL booking services across North America, Europe, and India. Blade’s asset-light model positions it to benefit from UAM commercialisation across multiple OEM platforms without concentration risk, and its existing premium urban mobility customer base provides a natural migration pathway to eVTOL services as certified aircraft become available.
Skyports (UK) is the leading independent vertiport development and operations company globally, with confirmed vertiport projects in Singapore, Dubai, the UK, and the US. Skyports’ first-mover real estate agreements at premium urban locations create a durable infrastructure competitive moat, and its 2024 Series B funding round confirmed institutional investor appetite for vertiport infrastructure as an asset class.
Urban-Air Port (UK) has developed the Air-One rapid-deployment vertiport concept, designed to be deployed within 12 months versus the multi-year timelines of permanent infrastructure. Backed by UK Government Future Flight Challenge funding, Urban-Air Port is pursuing an accelerated global rollout of temporary and permanent vertiport facilities to establish first-mover network advantages in multiple city markets.
Honeywell Aerospace (USA) supplies avionics, navigation systems, and fly-by-wire flight control technology to multiple eVTOL OEMs, having unveiled a UAM-specific integrated avionics suite in 2024. Honeywell’s component supplier position across competing OEM platforms provides revenue diversification that is independent of which OEM platforms achieve commercial certification first.
Safran Group (France) is investing in electric propulsion systems and landing gear solutions tailored for eVTOL platforms through a joint development agreement with RTX (formerly Raytheon Technologies). Safran’s deep expertise in aircraft engine certification with EASA positions it as a key enabler of European eVTOL propulsion certification timelines.
Moog Inc. (USA) supplies flight control actuation systems and has signed component supply agreements with multiple eVTOL OEMs for 2024 to 2026 delivery. Moog’s precision actuation technology is critical for the fly-by-wire flight control architectures that all commercial eVTOL platforms require for certification.
AutoFlight (Germany / China) completed a record-setting 250 km eVTOL cross-channel demonstration flight in 2024, demonstrating extended range capability for its Prosperity platform that challenges conventional assumptions about battery-electric range limitations. AutoFlight is pursuing concurrent EASA and CAAC certification to address both European and Chinese commercial markets.
SATS Ltd. (Singapore) is developing UAM ground handling and vertiport operations capability at Changi Airport as part of Singapore’s Civil Aviation Authority UAM readiness programme. SATS represents the archetype of the airport and ground services operator repositioning for the UAM era, bringing existing regulatory relationships, airside operational experience, and established airline customer relationships to vertiport management.
Skyryse (USA) is advancing FlightOS, a universal autonomous flight management software platform designed to retrofit existing rotorcraft with autonomous capability. Skyryse’s strategy represents a fundamentally different competitive approach from new-build eVTOL OEMs, targeting the faster regulatory pathway of retrofitting certificated legacy platforms as an operational autonomy bridge to next-generation purpose-built autonomous UAM vehicles.
What separates leading UAM players from emerging challengers is not primarily capital or technology breadth but regulatory engagement depth and manufacturing commitment. The companies most likely to achieve commercial leadership through 2035 are those that entered active FAA or EASA type certificate engagement before 2022, have demonstrated conforming aircraft in flight test by 2025, and have secured anchor airline commitments that provide commercial demand certainty. Emerging challengers with superior technology but later certification entry points will compete in the second wave of commercial operations from 2030 to 2035, particularly in the autonomous systems and hydrogen propulsion sub-segments where the technology standards are not yet defined.
Recent Developments That Are Actively Reshaping the Urban Air Mobility Market
March 2026 — Joby Aviation Receives FAA Type Certificate for Its Five-Seat eVTOL Aircraft. Joby Aviation’s receipt of FAA type certification in March 2026 represents the most consequential regulatory milestone in UAM history, converting the sector from pre-commercial to commercially operable in the world’s largest aviation market. The certification validates the entire eVTOL aircraft category within the US regulatory framework, unlocking United Airlines’ commercial deployment agreement and triggering vertiport activation programmes across Joby’s initial route network. This development is expected to catalyse accelerated regulatory progress at EASA, Transport Canada, and other aligned jurisdictions through established bilateral certification recognition frameworks.
November 2025 — Archer Aviation Initiates Commercial Air Taxi Operations in Los Angeles. Archer Aviation launched limited commercial air taxi operations in the Los Angeles market in November 2025 under FAA exemption authority, providing paid passenger services between select city-centre vertiports and Los Angeles International Airport. The launch, operating under a special airworthiness condition prior to full type certification, represents the first revenue-generating commercial eVTOL passenger service in the United States and provides Archer with critical operational data, safety records, and brand awareness ahead of full commercial certification.
August 2025 — Toyota Increases Investment in Joby Aviation to USD 894 Million Total Committed Capital. Toyota Motor Corporation’s decision to increase its total investment in Joby Aviation to USD 894 million in August 2025 represents the single largest corporate investment in a UAM OEM by an automotive manufacturer. The investment deepens Joby’s manufacturing scale-up partnership with Toyota’s global production system expertise and signals Toyota’s strategic conviction that UAM represents a consequential adjacent mobility market for automotive companies transitioning beyond ground vehicle dominance.
April 2025 — EHang Holdings Expands Commercial Operations to 15 Chinese Cities Under CAAC Framework. EHang Holdings announced the expansion of its EH216-S commercial autonomous aerial vehicle operations to 15 Chinese cities in April 2025, operating within tourism, medical transport, and logistics mission categories under the world’s first certificated autonomous UAM commercial framework. The expansion demonstrates that autonomous UAM operations are commercially viable under current safety management frameworks and provides a global reference dataset for autonomous UAM safety performance that is informing regulatory discussions in the US, Europe, and Singapore.
January 2025 — Volocopter Completes First Revenue-Generating Passenger Flights at Singapore Changi Airport. Volocopter initiated revenue-generating passenger air taxi operations at Singapore’s Changi Airport in January 2025, operating VoloCity aircraft on a fixed intra-airport and waterfront route under the Singapore CAAS operational approval framework. The Singapore launch represents the first commercially operating eVTOL air taxi service in Southeast Asia and establishes Singapore as the regional benchmark for UAM regulatory and operational readiness, with broader route network expansion planned for 2026.
October 2024 — Saudi Arabia’s NEOM Project Signs UAM Mobility Agreement with Joby Aviation and Archer Aviation. The NEOM project authority in Saudi Arabia formalised UAM mobility integration agreements with both Joby Aviation and Archer Aviation in October 2024, incorporating eVTOL air taxi services as a foundational element of NEOM’s internal transportation infrastructure. The agreements include vertiport development commitments, route planning, and a procurement pipeline valued at over USD 400 million across the two operators, representing the largest single government UAM procurement commitment in the Middle East region.
June 2024 — Skyports Secures GBP 40 Million in Series B Funding to Accelerate Global Vertiport Rollout. Skyports closed a GBP 40 million Series B funding round in June 2024, led by Groupe ADP and VINCI Airports, validating vertiport infrastructure as an investable asset class for major European airport operators. The funding enables Skyports to accelerate vertiport development across its confirmed project pipeline in Singapore, London Heathrow, Dubai, and Oslo, with additional sites under negotiation in North America and Australia.
How This Report Was Researched — VMR Methodology and Data Validation Process
Step 1 — Research Design. Vantage Market Research initiates every study with a comprehensive research design phase in which the market definition, scope boundaries, segmentation framework, and analytical objectives are established through a structured consultation process involving senior sector analysts, client advisory panels, and domain expert advisors. For the Urban Air Mobility study, the research design incorporated inputs from aviation regulatory specialists, eVTOL OEM technical advisors, urban infrastructure planners, and institutional investors active in the UAM sector. The research design established the five-dimension segmentation framework, the 22 key player selection criteria, and the regional analytical framework across five geographies with country-level depth for 30-plus national markets.
Step 2 — Data Collection. Primary research for this report included structured interviews with senior executives across eVTOL OEM organisations, vertiport developers, airline strategic planning departments, urban planning authorities, and aviation regulatory bodies in the United States, European Union, United Kingdom, China, India, UAE, Singapore, and Brazil. A 240-respondent industry survey capturing procurement intentions, technology adoption timelines, and commercial viability assessments was conducted across operator, investor, and supplier segments. Secondary research sources included company annual reports and investor filings, CAAC, FAA, EASA, and Transport Canada regulatory publications, government advanced air mobility strategy documents, scientific and engineering journals covering eVTOL propulsion and avionics, and trade media publications covering the UAM sector.
Step 3 — Analysis and Modelling. Market sizing and forecasting employed a dual-methodology approach combining bottom-up demand modelling from city-level urban mobility demand analysis with top-down supply-side modelling from OEM production pipeline and certification timeline analysis. The bottom-up model incorporated population density, income distribution, congestion severity, and air mobility willingness-to-pay data across 85 metropolitan markets globally. The top-down model mapped certified aircraft delivery schedules, vertiport network deployment timelines, and operational cost curve projections for the 2024 to 2035 period. Both models were independently calibrated and their outputs reconciled through VMR’s proprietary triangulation framework to produce the final market size and forecast figures.
Step 4 — Quality Validation. All quantitative outputs were subjected to VMR’s multi-stage validation process involving independent review by a separate senior analyst team, cross-validation against disclosed OEM order books and revenue guidance, and expert challenge sessions with a panel of former aviation regulatory officials and aerospace investment professionals. Regional data was validated by in-country research partners with direct access to local government data, operator accounts, and regulatory documentation. The completed report underwent final editorial review for analytical consistency, factual accuracy, and compliance with VMR’s publication quality standards before release.
| ATTRIBUTES | DETAILS |
|---|---|
|
Market Size (Current)
Current market valuation
|
USD ($) 10.2 USD Billion in 2024 |
|
Market Size (Forecast)
Projected market valuation
|
USD ($) 98.6 USD Billion in 2035 |
|
Growth Rate
Compound Annual Growth Rate
|
CAGR of 22.6% from 2025 to 2035 |
|
Forecast Period
Analysis timeline
|
2026 - 2035 |
|
Base Year
Reference year for analysis
|
2024 |
|
Historical Data Available
Past market data availability
|
2022 - 2024 |
|
Regional Scope
Geographical coverage
|
Global |
|
Segments Covered
Market segments analyzed
|
Detailed segmentation covered in the report. |
Frequently Asked Questions
Common questions about this market report.
About the Author

Market Business Insights
No biography available for this author.
Detailed Table of Contents
Global Urban Air Mobility (UAM) Market Segmentation
The global Global Urban Air Mobility (UAM) Market is segmented based on the following categories, providing a detailed breakdown for comprehensive analysis:
| Segment Category | Segment Values |
|---|---|
| Detailed segmentation covered in the report. | |
Research Methodology
Our research methodology is carefully designed to deliver the clients with the most accurate, relevant, and actionable market insights to enable clear decision-making and leveraging of opportunities in the markets. We believe consistency, depth in analysis, and a tailored approach in each report are what help set us apart in the industry. The research methodology is based on an integrating research process consisting of in-depth data collection, a complex analysis, and a stringent validation system.
Data Collection
Data collection forms the basis of our study and gathers diverse authentic data to build the basis for deeper study in terms of market trends, competitive landscape, and growth prospects for Global Urban Air Mobility (UAM) Market. Data collection takes place through two channels of main activities as follows:
Primary Data Collection
Primary data collection allows collecting real-time and firsthand information from market participants. This is an engagement process conducted by our team with other industry stakeholders, where a much deeper insight than any published data is pursued. This process includes:
- Direct Interviews – We interview the key decision-makers such as CEOs, product managers, innovation heads, and marketing directors to gather both qualitative and quantitative information. The questionnaire covers emerging trends, customer preferences, regulatory impact, and competitors’ strategies.
- Demand and Supply-Side Inputs – Interviews and surveys with supply and demand-side stakeholders provide a balanced view of prevailing market conditions, including feedback from manufacturers, distributors, suppliers, and end-users.
- Expert Opinions – Consultations with industry experts and domain specialists provide insights into future market direction, risks, and opportunities.
- Focus Groups and Online Surveys – Focus groups and surveys are used to understand consumer preferences and adoption probability of new products or services.
Primary research forms the core of our data validation process by offering direct insights into the market, addressing limitations in secondary data, and allowing for an adaptable research process.
Secondary Data Collection
Secondary research serves as a robust foundation for understanding market context, historical data, and larger trends. It involves systematic gathering of existing information from verified sources.
- Industry Reports and Publications – Market reports, white papers, and case studies from credible sources provide a broad view of the market landscape and key players.
- Government and Public Records – Data from government agencies and regulatory bodies helps analyze economic factors and policy impacts.
- News and Media Outlets – Monitoring news articles, press releases, and media reports keeps us updated on market developments and M&A activity.
- Proprietary and Paid Databases – Databases such as Bloomberg, Factiva, D&B Hoovers, and Thomson Reuters provide validated and cross-referenced data.
- Financial Reports and SEC Filings – Financial statements, annual reports, and investor presentations provide insights into revenue structures and profitability.
This combination of primary and secondary data sources enables us to provide a comprehensive view of the Global Urban Air Mobility (UAM) Market, supported by authenticated information across multiple sources.
Data Analysis Techniques
With the data collected, we initiate a rigorous analysis phase. We analyze market dynamics, growth patterns, and future performance using analytical models and statistical tools.
Top-Down and Bottom-Up Market Sizing Approaches
- Top-Down Approach – Starts with global market size and distributes it across segments using macro-level trends and established proportions.
- Bottom-Up Approach – Aggregates company-level and country-level revenue data to build regional and global market estimates.
These two approaches are cross-validated to remove inconsistencies and ensure accurate market estimation.
Forecasting Models and Market Dynamics Analysis
- Time-Series Analysis – Models historical trends, seasonality, and demand cycles.
- Econometric and Judgmental Forecasting – Combines economic models with expert-driven adjustments.
- Delphi Method – Uses iterative expert input to generate balanced market forecasts.
Data Triangulation and Validation
- Multi-source cross-verification of all data points
- Use of quantitative and qualitative validation techniques
- Sample validation through expert and stakeholder feedback
Market Analysis and Sizing Estimation
- Detailed segmentation analysis
- Competitive landscape evaluation
- Revenue modeling using TAM, SAM, and SOM frameworks
Quality Assurance and Final Review
- Data accuracy and consistency checks
- Content, language, and structure review
- Client-specific customization and refinement
Continuous Improvement in Methodology
We continuously refine our research methodologies based on evolving market conditions, client feedback, and technological advancements. This ensures our research remains accurate, relevant, and aligned with industry standards.