

Market Overview: Why the Biliary Stents Market Stands at a Commercial and Clinical Inflection Point
The global biliary stents market was valued at USD 915.4million in 2026 and is projected to reach USD 2,052.8 million by 2036, expanding at a compound annual growth rate of 8.4%over the forecast period. This sustained growth trajectory reflects the intersection of rising global biliary disease burden, rapid advances in endoscopic technologies, and broadening procedural access across emerging healthcare economies. Biliary stents are tubular prosthetic devices implanted within the bile duct to restore or maintain bile flow when the duct becomes obstructed, narrowed, or damaged. The obstruction may be malignant, arising from pancreatic, cholangiocarcinoma, or ampullary cancers, or benign, resulting from inflammatory strictures, primary sclerosing cholangitis, or post-surgical complications. In either case, the stent serves as a structural bridge, preventing life-threatening cholestasis and enabling palliative or curative treatment plans to proceed.
Over the past five years spanning c through 2026, the market has been shaped by three convergent macro forces. First, the global incidence of pancreatic and hepatobiliary cancers has risen measurably, with pancreatic cancer alone accounting for approximately 495,000 new diagnoses globally in 2023 according to the World Health Organization’s Global Cancer Observatory data. Because biliary obstruction is a near-universal complication of pancreatic head malignancies, the oncology disease burden directly drives procedural volume. Second, endoscopic retrograde cholangiopancreatography (ERCP) has solidified its position as the gold-standard access modality for biliary stenting, and the diffusion of ERCP capability into tier-2 and tier-3 hospitals across Asia Pacific and Latin America has expanded the addressable market well beyond the major academic medical centers that historically captured most procedural volume. Third, the development of endoscopic ultrasound-guided biliary drainage (EUS-BD) as an alternative access route has opened procedural options for patients where conventional ERCP is anatomically challenging, further growing the total stent-implantable patient population.
The post-pandemic period from 2022 onward introduced both headwinds and tailwinds for market participants. Deferred elective and semi-elective biliary procedures during COVID-19 lockdowns created a backlog of cases that accelerated procedural recovery in 2022 and 2023 beyond baseline trend growth. Simultaneously, supply chain disruptions affecting nitinol wire, fluoropolymer coating materials, and precision-machined delivery systems forced manufacturers to requalify suppliers, extend lead times, and absorb higher input costs. These pressures are now largely resolved, with most tier-1 manufacturers having regionalized critical component sourcing by 2026. The market enters the 2026 to 2036 forecast horizon in a structurally sound position, with demand fundamentals strengthening and supply chain resilience materially improved relative to 2021 to 2022 conditions.

The biliary stents market sits at the intersection of three broader industry megatrends that will amplify growth through 2036. The aging of the global population, particularly in Japan, Western Europe, and North America, is expanding the cohort most susceptible to both malignant biliary disease and benign biliary complications from gallstone disease and chronic pancreatitis. The digital integration of endoscopy suites, including AI-assisted image analysis for stricture characterization and stent sizing, is accelerating procedural precision and reducing complication rates, which in turn lowers the barrier to stent adoption. And the sustainability imperative within medical device procurement is creating commercial opportunity for biodegradable and bioabsorbable stent technologies that eliminate the need for a second retrieval procedure, a development with transformative implications for benign indication segments.
Key Trends Reshaping the Biliary Stents Market Landscape
The Emergence of Biodegradable Biliary Stents Is Redefining the Benign Stricture Treatment Paradigm
Biodegradable biliary stents, fabricated from polydioxanone, poly-L-lactic acid, or similar bioabsorbable polymers, are gaining meaningful clinical traction as a solution to the central limitation of conventional stenting in benign strictures: the need for scheduled stent exchange every three to six months. ELLA-CS’s CE-approved biodegradable biliary stent, cleared in 2023, has emerged as the benchmark device in European clinical practice for post-anastomotic strictures following liver transplantation. The commercial implications are significant. A biodegradable stent that sustains radial force across a six-to-twelve-month remodelling window before controlled resorption eliminates two to four ERCP procedures per patient episode, reducing healthcare system cost and patient procedural burden simultaneously. Payors in Germany, France, and the Netherlands have begun incorporating biodegradable stent economics into reimbursement pathway reviews, which is expected to accelerate adoption materially from 2025 onward.
EUS-Guided Biliary Drainage Is Expanding the Stentable Patient Population Beyond Conventional ERCP Access
Endoscopic ultrasound-guided biliary drainage has transitioned from an experimental salvage technique to a first-line procedural alternative in high-volume hepatopancreatobiliary centres, particularly for patients with surgically altered anatomy, periampullary malignancies causing duodenal obstruction, or failed conventional ERCP cannulation. The commercial consequence for stent manufacturers is a new category of devices specifically engineered for EUS-BD access, including lumen-apposing metal stents (LAMS) designed for hepaticogastrostomy and choledochoduodenostomy approaches. Boston Scientific’s Hot AXIOS system and Leufen Medical’s AXIOM platform represent the leading commercial manifestations of this trend. As EUS-BD competency diffuses from academic referral centres to community tertiary hospitals driven by subspecialty training program growth, the addressable market for dedicated EUS-biliary stents will expand substantially through the forecast period.
Artificial Intelligence Integration in Endoscopy Is Improving Stent Selection Precision and Procedural Outcomes
Computer-aided detection and diagnostic AI systems embedded within endoscopy workstations are beginning to influence biliary stent selection through real-time stricture characterization, luminal diameter measurement, and stent length recommendation. Medtronic’s 2026 partnership with GI Genius-adjacent AI platforms specifically incorporates biliary guidance modules. The commercial implication for stent manufacturers is twofold: device interoperability with endoscopy AI ecosystems is becoming a product differentiator, and AI-driven outcomes data is generating real-world evidence that supports reimbursement expansion for premium covered metal stents in markets where coverage has historically lagged clinical practice. Manufacturers investing in co-development agreements with endoscopy AI vendors are positioned to capture first-mover advantage in this emerging interoperability segment.
Antimicrobial and Drug-Eluting Stent Coatings Are Addressing the Market’s Most Persistent Clinical Limitation
Stent occlusion from bacterial biofilm formation and biliary sludge deposition remains the single greatest cause of stent failure, typically requiring unplanned re-intervention at three to six months for plastic stents and six to twelve months for uncovered metal stents. A new generation of antimicrobial coatings, including silver-ion impregnated polymer layers and rifampicin-eluting fluoropolymer matrices, is in active clinical development at leading manufacturers. Several academic hospital systems in South Korea and Germany published peer-reviewed data in 2026 demonstrating statistically significant reduction in stent occlusion rates with antimicrobial-coated prototypes versus standard covered SEMS. If even one of these coating technologies achieves regulatory clearance within the forecast period, it would represent the most consequential clinical advance in biliary stenting since the introduction of covered SEMS in the late 1990s, with corresponding premium pricing power and market share capture potential for the innovating manufacturer.
What Is Driving Growth and What Is Holding It Back: Drivers, Restraints and Opportunities
Market Drivers
Rising Global Incidence of Pancreatic and Hepatobiliary Cancers Is Generating Sustained Procedural Volume: Pancreatic cancer represents the single largest driver of biliary stent demand, as biliary obstruction occurs in approximately 70 to 80 percent of pancreatic head tumours. With global pancreatic cancer incidence rising at roughly 1 to 2 percent annually driven by aging populations, obesity prevalence, and improved diagnostic detection, the underlying patient population requiring palliative or bridging biliary stenting is growing in absolute terms every year. This demographic and epidemiological tailwind is irreversible over any medium-term planning horizon, providing a structurally reliable demand foundation for manufacturers regardless of competitive or macroeconomic fluctuation.
Expansion of ERCP Procedural Capability Into Secondary and Tertiary Hospitals Across Asia Pacific and Latin America: Historically, biliary stenting was concentrated in academic medical centres with subspecialty hepatopancreatobiliary units. The diffusion of ERCP training programs, the installation of modern endoscopy suites in tier-2 hospitals across China, India, Brazil, and Southeast Asia, and the development of government-sponsored training initiatives such as India’s National Programme for Prevention and Control of Cancer have collectively expanded the procedural base. Each new ERCP-capable centre represents an incremental market entry point for stent device manufacturers, and the geographic dispersion of these centres is now widening at an accelerating pace.
Shift Toward Minimally Invasive Interventional Gastroenterology Is Displacing Surgical Biliary Bypass: Surgical biliary bypass, once the standard approach for unresectable malignant biliary obstruction, has been largely supplanted by endoscopic stenting at high-volume centres owing to equivalent or superior outcomes with substantially lower morbidity, shorter hospitalization, and faster return to oncological therapy. This paradigm shift, now reflected in clinical guidelines from the European Society of Gastrointestinal Endoscopy and the American Society for Gastrointestinal Endoscopy, has permanently reallocated procedural volume toward endoscopic stenting, and the continued adoption of these guidelines in emerging markets will sustain this driver through the forecast period.
Technological Advances in Self-Expandable Metal Stent Design Are Increasing Patency and Driving Repeat Device Uptake: Manufacturers have achieved meaningful improvements in SEMS radial force profiles, foreshortening reduction, and anti-migration geometry through iterative nitinol braid engineering and heat-treatment refinements. Longer stent patency directly reduces re-intervention rates, which while reducing per-patient stent volume, simultaneously expands the population of clinicians willing to adopt SEMS over plastic stents for moderate-complexity cases. The net commercial effect is positive: migration from lower-priced plastic stents to higher-priced metal stents represents an average selling price uplift of three to eight times per procedure, more than offsetting any reduction in replacement frequency.
Growth of Ambulatory Surgical Centres as a Preferred ERCP Site Is Expanding the Addressable Facility Market: ASCs in the United States accounted for an estimated 28 percent of ERCP procedures in 2026, up from approximately 18 percent in 2021 according to procedure utilization analyses in gastroenterology literature. This channel shift is driven by cost advantages, patient preference, and CMS reimbursement parity decisions. For device manufacturers, ASC penetration requires tailored distribution models, tray-based implant stocking programs, and streamlined ordering platforms, creating both a challenge and a strategic opportunity to establish preferential relationships in a rapidly growing procedural site category.
Favourable Reimbursement Environments in the United States, Germany, and Japan Are Supporting Premium Device Adoption: ERCP with metal stent placement is reimbursed at substantially higher rates than plastic stent procedures under U.S. Medicare’s outpatient prospective payment system, German DRG coding, and Japan’s NHI fee schedule. These reimbursement structures create a favourable economic incentive for facilities to preferentially adopt covered SEMS for appropriate indications, directly supporting the revenue mix shift toward higher-margin metal stent products at the manufacturer level.
Post-Transplant and Post-Surgical Biliary Stricture Management Is Creating a Growing Benign Indication Segment: The global volume of liver transplantations has grown steadily, with biliary anastomotic strictures occurring in 10 to 25 percent of recipients. Post-cholecystectomy bile duct injuries, post-pancreatectomy strictures, and chronic pancreatitis-related biliary compression collectively represent a substantial and growing population requiring repeated biliary intervention. This benign indication segment is particularly receptive to biodegradable stent technology and multiple-stent-in-stent plastic stenting protocols, representing a distinct growth driver independent of the oncology-driven malignant indication market.
Market Restraints
High Procedural Complexity and Operator Skill Dependency Limit Adoption in Under-Resourced Settings: ERCP with stent placement is a technically demanding procedure associated with serious adverse events including pancreatitis, bleeding, perforation, and cholangitis in 5 to 10 percent of cases even in experienced hands. The skill dependency creates a ceiling on geographic market penetration, particularly in rural and semi-urban healthcare settings in Sub-Saharan Africa, South Asia, and Latin America where subspecialty endoscopy training infrastructure is limited. This constraint cannot be resolved through device innovation alone and requires sustained investment in training programs and procedural simulation, limiting the pace at which addressable market expansion in underserved regions can be achieved.
Stent Occlusion and Migration Remain Unresolved Clinical Limitations That Restrict Long-Term Market Value per Patient: Despite technological advances, biliary stent occlusion from sludge deposition, tumour ingrowth, or biofilm formation remains prevalent, typically necessitating stent exchange within 3 to 12 months. Occlusion episodes requiring emergency ERCP generate clinical risk and healthcare cost, creating hesitancy among some payors to expand covered SEMS reimbursement in markets where cost-containment pressures are significant. Until antimicrobial or drug-eluting coating technologies achieve regulatory approval and clinical validation at scale, this limitation will constrain market growth in value-sensitive healthcare systems.
Reimbursement Heterogeneity Across Emerging Markets Creates Unpredictable Revenue Visibility for Global Manufacturers: While premium biliary stent reimbursement is well-established in North America, Western Europe, and Japan, reimbursement structures in China, Brazil, Southeast Asia, and the Middle East are fragmented, inconsistent across facility types, and subject to periodic reform. In China’s volume-based procurement framework, medical devices including gastrointestinal implants have faced centralized pricing pressure that has compressed average selling prices by 20 to 40 percent for domestic tenders. This reimbursement uncertainty complicates long-range investment planning and pricing strategy for multinational manufacturers seeking to grow in high-volume emerging markets.
Intense Price Competition From Domestic Manufacturers in China and South Korea Is Eroding Margins for Imported Devices: Domestic Chinese manufacturers including Micro-Tech Nanjing and regional Korean specialists including Taewoong Medical and M.I. Tech produce CE-marked and locally certified SEMS at price points 30 to 50 percent below comparable Western products. In markets where reimbursement is commoditized or where hospital procurement is driven by lowest-price tendering, these domestic alternatives are effectively displacing imported devices. The competitive pressure is particularly acute in China’s public hospital segment and in tender-driven healthcare systems across Southeast Asia and the Middle East.
Regulatory Pathway Complexity Under MDR and Post-Market Surveillance Requirements Is Increasing Compliance Costs: The transition to the European Union Medical Device Regulation, fully effective since May 2026 for devices under the prior In Vitro Diagnostic directive timeline, has imposed substantially more rigorous clinical data, post-market clinical follow-up, and notified body review requirements on biliary stent manufacturers. Several smaller European and Asian manufacturers have faced delays in MDR certification, temporarily restricting their product availability in EU markets. The compliance cost increase disproportionately impacts smaller innovative firms, potentially consolidating market access around the largest well-resourced manufacturers and slowing the introduction of novel stent technologies into European clinical practice.
Market Opportunities
Biodegradable Stent Technology Represents a Multi-Hundred-Million-Dollar Underserved Segment With First-Mover Reward: The benign biliary stricture segment accounts for approximately 26 percent of total biliary stent procedures globally but is served almost entirely by plastic stents requiring multiple exchanges. A fully validated biodegradable biliary stent that eliminates repeat ERCP in this indication would represent not merely an incremental improvement but a category-creating clinical and commercial development. With ELLA-CS’s CE approval in place and clinical registry data accumulating in 2026 and 2025, the regulatory pathway for biodegradable biliary stents is becoming clearer. Manufacturers and investors who move decisively in this segment over the 2025 to 2028 period are positioned to establish durable category leadership in a niche that existing stent majors have underinvested in.
Digital Health Integration and Stent Registry Platforms Create Data-Driven Value Propositions for Payors and Providers: An emerging opportunity exists for manufacturers to build connected stent management ecosystems that capture post-implant patient data, flag early signs of occlusion through biomarker monitoring or imaging integration, and optimize stent exchange timing. Such platforms would transform the biliary stent from a commodity device into a managed service with recurring engagement value, supporting subscription or outcomes-based contracting models with hospital systems. The infrastructure for these platforms, including ERCP procedure documentation systems and EHR integration, already exists at most high-volume centres; the commercial opportunity lies in connecting device performance data to these existing workflows.
The Middle East and Africa Region Offers Underpenetrated Premium Stent Volume as Healthcare Infrastructure Investment Accelerates: Saudi Arabia’s Vision 2030 healthcare investment program and the UAE’s National Health Strategy 2030 collectively commit hundreds of billions of riyals to hospital capacity expansion, specialised medical equipment procurement, and physician training. Within this investment landscape, interventional gastroenterology and hepatopancreatobiliary capabilities are being prioritized at flagship hospitals in Riyadh, Dubai, Abu Dhabi, and Jeddah. Manufacturers who establish direct distributor relationships, clinical training programs, and government tender registrations in the Gulf Cooperation Council region during the 2025 to 2028 window will be well-positioned to capture the premium stent volume that will flow from this infrastructure investment.
- ■ By Product Type
- ■ By Application
- ■ By End-User
- ■ By Region
| Year | 1st QTR | 2nd QTR | 3rd QTR | 4th QTR |
|---|---|---|---|---|
| 2025 | XX Mn/Bn | XX Mn/Bn | XX Mn/Bn | XX Mn/Bn |
| 2024 | XX Mn/Bn | XX Mn/Bn | XX Mn/Bn | XX Mn/Bn |
| 2023 | XX Mn/Bn | XX Mn/Bn | XX Mn/Bn | XX Mn/Bn |
| 2026 | XX Mn/Bn | 2031 | XX Mn/Bn |
| 2027 | XX Mn/Bn | 2032 | XX Mn/Bn |
| 2028 | XX Mn/Bn | 2033 | XX Mn/Bn |
| 2029 | XX Mn/Bn | 2034 | XX Mn/Bn |
| 2030 | XX Mn/Bn | 2035 | XX Mn/Bn |
How the Biliary Stents Market Divides: A Full Segmentation Analysis
Segmentation Overview Table
| Segment Category | Sub-Segment | Market Share (2026) | CAGR (2026–2036) |
| By Type
|
Self-Expandable Metal Stents (SEMS) | 42% | 7.4% |
| Plastic Stents | 31% | 5.2% | |
| Covered Metal Stents | 15% | 7.9% | |
| Uncovered Metal Stents | 8% | 6.1% | |
| Biodegradable Stents | 4% | 13.2% | |
| By Application | Malignant Biliary Obstruction | 48% | 7.6% |
| Benign Biliary Strictures | 26% | 6.4% | |
| Primary Sclerosing Cholangitis | 12% | 7.0% | |
| Choledocholithiasis | 9% | 5.8% | |
| Others | 5% | 5.5% | |
| By Material
|
Nitinol | 44% | 7.3% |
| Stainless Steel | 22% | 4.9% | |
| Polyethylene | 19% | 5.6% | |
| PTFE / Fluoropolymer | 9% | 6.8% | |
| Biodegradable Polymers | 6% | 14.1% | |
| By End User | Hospitals | 52% | 6.9% |
| Ambulatory Surgical Centers | 28% | 8.5% | |
| Specialty Clinics | 13% | 7.2% | |
| Others | 7% | 5.4% | |
| By Distribution | Direct Sales | 47% | 7.0% |
| Distributors | 35% | 6.5% | |
| Online / E-Commerce | 18% | 11.3% | |
| By Region | North America | 38% | 6.8% |
| Europe | 28% | 6.5% | |
| Asia Pacific | 22% | 9.4% | |
| Latin America | 7% | 7.8% | |
| Middle East and Africa | 5% | 8.2% |
By Type: Self-Expandable Metal Stents Lead While Biodegradable Variants Record the Fastest Growth
Self-expandable metal stents held the dominant share of approximately 42 percent of the global biliary stents market in 2026 and are expected to maintain leadership through 2036, expanding at a CAGR of 7.4 percent. SEMS offer superior radial force and longer patency compared with plastic alternatives, making them the standard of care for malignant biliary obstruction. Covered SEMS prevent tumour ingrowth at the expense of higher migration risk, while uncovered SEMS provide greater anchoring stability with reduced occlusion-prevention efficacy. The covered variant is growing faster at an estimated 7.9 percent CAGR, driven by adoption in longer-term palliative cases where patency duration is the primary clinical objective.
Plastic stents retain a 31 percent market share, sustained by their significantly lower cost, ease of exchange, and suitability for benign indications where long-term implantation is not intended. The plastic stent segment is growing at a more modest 5.2 percent CAGR, reflecting the gradual substitution pressure from SEMS in clinically appropriate cases and the early penetration of biodegradable alternatives in benign indication settings.
Biodegradable stents, while representing only 4 percent of current market value, are the fastest-growing type segment at a projected CAGR of 13.2 percent through 2036. Clinical validation from European liver transplant programmes, combined with regulatory clearances achieved in 2023 and 2026, is creating the foundation for commercial scaling. The segment’s small current base amplifies its CAGR, but the absolute revenue opportunity by 2036 is substantial, with the segment projected to represent a USD 60 to 80 million annual revenue category at current growth trajectory assumptions.
By Application: Malignant Obstruction Anchors the Market While Benign Strictures Offer Differentiated Growth
Malignant biliary obstruction accounted for approximately 48 percent of the total market by application in 2026 and is growing at 7.6 percent CAGR. Pancreatic adenocarcinoma is the single most common underlying diagnosis, followed by cholangiocarcinoma and ampullary carcinoma. In all three cancer types, biliary stenting plays a critical palliative role and increasingly a neoadjuvant bridging role, allowing patients to achieve adequate bilirubin reduction to qualify for chemotherapy protocols such as FOLFIRINOX and gemcitabine-based regimens. The growing adoption of neoadjuvant chemotherapy for borderline resectable pancreatic cancer has specifically increased the strategic importance of pre-operative biliary stenting in this subpopulation.
Benign biliary strictures represent 26 percent of the market and are growing at 6.4 percent CAGR. This segment encompasses post-liver-transplant anastomotic strictures, chronic pancreatitis-related biliary compression, and post-cholecystectomy bile duct injuries. The management of benign strictures typically involves a protracted course of sequentially upgraded stenting, meaning higher per-patient device utilization and recurring procedural relationships between manufacturers and clinical teams. Choledocholithiasis, the fourth largest application segment at 9 percent share, is driven by the global incidence of bile duct stones complicating cholecystectomy and requiring ERCP-based stone extraction with temporary stenting.
By Distribution Channel: Direct Sales Lead but E-Commerce Is the Fastest-Growing Channel
Direct sales through hospital procurement departments and dedicated sales force engagement accounted for approximately 47 percent of market revenue in 2026. This channel dominates in North America and Western Europe, where hospital GPO contracts and IDN-level purchasing agreements make direct manufacturer-to-facility relationships commercially critical. Distributors retained approximately 35 percent of market revenue, serving as the primary go-to-market mechanism in Asia Pacific, Latin America, and the Middle East, where the geographic complexity and regulatory heterogeneity of individual country markets make direct commercial infrastructure economically impractical for most manufacturers.
Online and e-commerce procurement channels accounted for approximately 18 percent of market revenue in 2026 but are growing at the fastest channel CAGR of 11.3 percent through 2036. This growth is concentrated in two distinct sub-channels: institutional procurement platforms operated by hospital groups and GPOs, which are digitising their ordering workflows; and direct-to-distributor digital platforms in emerging markets where traditional field sales infrastructure is thin. The ASC segment is particularly receptive to online procurement of biliary stent trays, reflecting the operational efficiency priorities of the ambulatory care environment.
Share
Share
Share
Share
Share
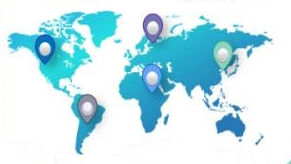
Where in the World the Biliary Stents Market Is Growing: A Regional Analysis Across All Five Geographies
North America Commands the Largest Market Share, Driven by Advanced Healthcare Infrastructure and Reimbursement Clarity
North America accounted for approximately 38 percent of the global biliary stents market in 2026, representing a market value of approximately USD 285.9 million. The United States contributes the overwhelming majority of regional revenue, supported by a healthcare system that combines high procedural volumes, favourable CMS reimbursement for ERCP with stent placement, and strong commercial insurance coverage for advanced endoscopic interventions. Canada contributes approximately 6 to 8 percent of regional revenue, with biliary stent adoption concentrated in major urban teaching hospitals affiliated with national cancer care networks.
The U.S. market is evolving toward ASC-based ERCP delivery, premium SEMS adoption, and digital integration of endoscopy suites, each of which benefits manufacturers with diversified product portfolios and strong commercial sales teams capable of navigating multi-stakeholder procurement environments. Trade tariff exposure for imported components, particularly nitinol wire sourced from Asian suppliers, has prompted several manufacturers to accelerate domestic supply chain localization initiatives, a trend that will strengthen North American manufacturing capacity through the forecast period. The North American market is expected to grow at approximately 6.8 percent CAGR through 2036.
Europe Advances on Regulatory Rigor and Premium Device Adoption Amid the MDR Transition
Europe represented approximately 28 percent of global market value in 2026, equivalent to approximately USD 210.6 million. Germany and France are the two largest country markets within the region, collectively accounting for approximately 45 percent of European revenue. Germany’s strong hepatopancreatobiliary surgical and endoscopy infrastructure, combined with its DRG-based reimbursement that supports metal stent adoption, makes it the leading European volume market. France’s comprehensive oncology care networks and clinical trial environment have made it an early adopter of covered SEMS innovations and a key geography for biodegradable stent clinical development programmes.
The EU MDR transition has had a dual effect on the European biliary stents market. Incumbent manufacturers with established notified body relationships have maintained or strengthened their market positions, while smaller innovative firms have experienced certification delays that temporarily restricted product availability. The United Kingdom, operating under its own post-Brexit UKCA regulatory framework, has shown willingness to leverage Approved Body certificates from EU notified bodies under transitional arrangements, maintaining competitive device availability in a market characterized by NHS procurement efficiency pressures. European market growth is projected at approximately 6.5 percent CAGR through 2036.
Asia Pacific Represents the Highest Absolute Growth Opportunity, Led by China, India, and Southeast Asia’s Expanding ERCP Capacity
Asia Pacific accounted for approximately 22 percent of the global biliary stents market in 2026, representing approximately USD 165.5 million, but is expected to be the fastest-growing region through 2036 at a CAGR of approximately 9.4 percent. China is the dominant country market within the region, driven by a massive patient population, rapid expansion of third-level hospital ERCP capability, and a domestic manufacturing ecosystem producing competitively priced SEMS that serve both the domestic market and export to other emerging markets. However, China’s volume-based procurement programme has imposed meaningful average selling price pressure on imported devices, shifting competitive advantage toward domestic manufacturers for price-sensitive indications while preserving a premium segment at leading academic hospitals for innovative imported products.
India represents the highest-growth country market within Asia Pacific at an estimated 11 to 12 percent CAGR, driven by the combination of rising biliary cancer incidence, National Health Mission infrastructure investments, and the expansion of private hospital chains into tier-2 cities. The Ayushman Bharat PM-JAY insurance programme is gradually extending coverage to gastrointestinal oncology procedures at empanelled hospitals, creating new reimbursed procedural volume for stent manufacturers. Japan remains a high-value stable market characterized by rigorous regulatory standards under PMDA oversight, strong physician preference for domestically manufactured devices from Olympus and Piolax, and a well-reimbursed ERCP fee schedule under the National Health Insurance programme. Southeast Asia, including Thailand, Vietnam, Indonesia, and Malaysia, is an emerging high-growth subregion where healthcare system investment and medical tourism create growing procedural volume.
Latin America Offers Underpenetrated Volume With Brazil as the Dominant Commercial Opportunity
Latin America accounted for approximately 7 percent of global market value in 2026, equivalent to approximately USD 52.7 million, growing at an estimated 7.8 percent CAGR through 2036. Brazil is the dominant country market within the region, accounting for approximately 55 to 60 percent of regional stent revenue, driven by a large urban hospital network, active ERCP training programs at major gastrointestinal oncology centres in São Paulo and Rio de Janeiro, and a growing private health insurance market that is expanding access to premium endoscopic interventions. The public healthcare system through SUS operates under significant budget constraints that limit premium SEMS adoption in the public sector, while the private sector is increasingly aligned with international clinical guidelines supporting metal stent adoption for appropriate malignant indications. Distribution infrastructure fragmentation across Brazil’s geographically vast territory remains a constraint on achieving consistent national market penetration for manufacturers seeking to grow beyond the major metropolitan centres.
Middle East and Africa Present an Emerging Opportunity as Healthcare Infrastructure Investment Drives Premium Device Adoption
The Middle East and Africa region accounted for approximately 5 percent of global market value in 2026, equivalent to approximately USD 37.6 million, growing at an estimated 8.2 percent CAGR through 2036. Growth within the region is heavily concentrated in the Gulf Cooperation Council countries, with Saudi Arabia and the UAE collectively representing approximately 60 to 65 percent of regional stent revenue. Saudi Arabia’s Vision 2030 healthcare expansion, which includes the construction of multiple new tertiary hospital facilities and the recruitment of internationally trained hepatopancreatobiliary specialists, is creating direct procedural volume uplift for premium stent products. The UAE’s position as a regional medical tourism hub, particularly through Medcare and Cleveland Clinic Abu Dhabi facilities, channels complex biliary cases from across the GCC and North Africa into a high-capability procedural environment receptive to internationally validated premium stent technologies. Sub-Saharan Africa remains at an early stage of ERCP infrastructure development, but South Africa’s Johannesburg and Cape Town hospital networks represent anchor accounts for manufacturers seeking initial MEA market entry.
The Competitive Landscape: Who Leads, How They Compete and What Separates the Leaders
The global biliary stents market exhibits a moderately consolidated competitive structure, with the top five manufacturers, Boston Scientific, Cook Medical, Medtronic, Olympus, and Taewoong Medical, collectively accounting for an estimated 55 to 60 percent of global market revenue. The remaining 40 to 45 percent is served by a fragmented field of regional specialists, domestic manufacturers in China and South Korea, and innovative niche players. Competitive intensity is highest in the SEMS segment, where product differentiation based on stent architecture, coating technology, and delivery system ergonomics is most commercially significant, and lowest in the commodity plastic stent segment, where price competition dominates.
Top 20 Key Players in the Global Biliary Stents Market
| Company | Country | Strategic Focus | Recent Initiative |
| Boston Scientific Corporation | USA | Full-spectrum biliary portfolio; SEMS innovation | Launched WallFlex Biliary RX Stent upgrades, 2026 |
| Cook Medical | USA | Plastic and metal stent breadth; endoscopy integration | Expanded Evolution biliary stent line across APAC, 2026 |
| Medtronic plc | Ireland | Minimally invasive GI devices; digital integration | Partnership with AI-guided endoscopy platform, 2026 |
| Olympus Corporation | Japan | Endoscopy-driven biliary access; covered SEMS | Launched EUS-guided stent system in Japan, 2023 |
| Abbott Laboratories | USA | Vascular and structural device synergies | Strategic review of GI stent pipeline, 2026 |
| Taewoong Medical | South Korea | SEMS manufacturing; fully covered nitinol stents | FDA 510(k) clearance for NITI-S biliary stent, 2023 |
| M.I. Tech Co. Ltd. | South Korea | Covered and uncovered SEMS; export-led growth | New EU distribution agreement signed, Q1 2025 |
| TaeWoong-USA | USA | U.S. distribution for Korean-origin SEMS | Expanded hospital network coverage, 2026 |
| Hobbs Medical | USA | Specialty biliary drainage catheters and stents | New lumen-apposing stent prototype filed, 2025 |
| BD (Becton, Dickinson) | USA | Broad GI/hepatobiliary device portfolio | Acquired biliary drainage start-up, Q2 2026 |
| Micro-Tech (Nanjing) | China | Low-cost SEMS; Asia-Pacific volume growth | Cleared CE Mark for covered metal biliary stent, 2023 |
| EndoChoice (Fujifilm) | USA/Japan | Endoscopic accessories; biliary tools | Integration into Fujifilm’s GI platform, 2023 |
| ELLA-CS | Czech Republic | Biodegradable stents; benign stricture focus | CE-approved biodegradable biliary stent, 2023 |
| Leufen Medical | Germany | EUS-guided drainage stents; lumen-apposing design | European launch of AXIOM biliary LAMS, 2026 |
| GORE Medical (W.L. Gore) | USA | ePTFE-covered biliary stents for long patency | Clinical data publication on extended patency, 2026 |
| Cantel Medical (Medivators) | USA | Infection control and endoscopy adjuncts | Integration into Medline endoscopy strategy, 2026 |
| Piolax Medical Devices | Japan | Specialty plastic stents; Japanese hospital network | New pigtail biliary stent product line, 2026 |
| Diagmed Healthcare | UK | UK/EU biliary and GI distribution | Launched Cook Medical distribution expansion, 2026 |
| Endo-Flex GmbH | Germany | Flexible plastic biliary stents; European market | CE MDR-compliant product recertification, 2026 |
| Conmed Corporation | USA | GI endoscopy tools; biliary access devices | Expanded biliary catheter range in hospital GPOs, 2026 |
Leading players are increasingly differentiating through clinical evidence generation rather than device specification alone. Boston Scientific’s WallFlex platform, for instance, has accumulated one of the largest prospective clinical data sets in biliary stenting, enabling health economic arguments that justify premium pricing relative to lower-cost alternatives in GPO negotiations. Cook Medical’s breadth across both plastic and metal segments allows it to serve as a single-vendor solution for many facility procurement departments, reducing complexity and strengthening account loyalty. Taewoong Medical’s FDA 510(k) clearance strategy for its NITI-S platform has enabled it to compete for U.S. premium segment share at pricing below tier-1 Western manufacturers, a positioning that has proven effective in cost-sensitive rural and regional hospital markets.
Mergers, acquisitions, and partnerships are reshaping competitive boundaries. BD’s acquisition of a biliary drainage start-up in Q2 2026 signalled the intention of the diagnostics and vascular access major to expand its interventional GI footprint, potentially creating a new scale competitor in the biliary device space. Fujifilm’s integration of EndoChoice into its GI platform has created a vertical endoscope-plus-accessory offering that positions biliary stents as part of a bundled value proposition rather than a standalone device purchase. These dynamics suggest continued consolidation activity through the forecast period, with the most likely acquisition targets being innovative biodegradable stent developers and EUS-guided drainage device specialists.
Recent Developments That Are Actively Reshaping the Biliary Stents Market
March 2025: M.I. Tech Co. Ltd. Signed a New European Distribution Agreement Expanding SEMS Market Access: South Korean manufacturer M.I. Tech finalised a pan-European distribution partnership to expand commercial reach for its fully covered and partially covered nitinol SEMS range across Germany, France, and Benelux markets. The agreement, executed in Q1 2025, is expected to materially grow the company’s European market revenue within two years and signals growing international commercial ambition from Asian specialist manufacturers that had previously concentrated on domestic and nearby Asian market channels.
January 2025: Hobbs Medical Filed a Novel Lumen-Apposing Stent Prototype for Biliary Applications: U.S.-based specialty medical device developer Hobbs Medical advanced a new lumen-apposing metal stent design specifically engineered for EUS-guided hepaticogastrostomy drainage to the U.S. patent and device filing stage in early 2025. The design incorporates a dual-flange saddle geometry optimized for biliary access geometries distinct from the gastric and pancreatic indications where LAMS technology was originally commercialized, addressing a clinical gap identified in high-volume EUS-BD centres.
September 2026: Leufen Medical Launched the AXIOM Biliary LAMS Platform in European Markets: German medical device company Leufen Medical completed the commercial launch of its AXIOM lumen-apposing metal stent system for EUS-guided biliary drainage across major European markets in Q3 2026. The product received CE Mark under the MDR framework, making it one of the first EUS-specific biliary LAMS systems to achieve full EU regulatory compliance under the new regulatory regime. Clinical adoption at leading German and Dutch hepatopancreatobiliary centres has progressed rapidly since launch.
June 2026: BD (Becton, Dickinson) Acquired a Biliary Drainage Technology Start-up: BD completed the acquisition of a biliary drainage and stent technology start-up in Q2 2026, adding proprietary biliary access catheter and metal stent intellectual property to its growing interventional GI portfolio. The acquisition represents a strategic pivot for BD toward the hepatopancreatobiliary space and may signal the development of integrated biliary access and stent delivery systems under the BD brand. The financial terms were not disclosed, but industry analysts estimate the acquisition valued the target at approximately USD 150 to 200 million.
April 2026: Medtronic Partnered with an AI-Guided Endoscopy Platform for Biliary Stent Integration: Medtronic announced a strategic partnership with an AI-guided gastrointestinal endoscopy platform developer to integrate biliary stricture characterization and stent sizing algorithms into its endoscopy workflow solutions in April 2026. The partnership marks a departure from pure hardware-focused device strategy toward a device-plus-intelligence value proposition, positioning Medtronic to compete on procedural efficiency and outcome quality metrics in addition to device performance specifications.
November 2023: ELLA-CS Received CE Approval for Its Biodegradable Biliary Stent: Czech Republic-based ELLA-CS received CE marking for its biodegradable biliary stent in November 2023, becoming the first commercially available biodegradable biliary stent certified under EU regulatory frameworks. The approval was based on clinical data from European liver transplant centres demonstrating adequate radial force maintenance and controlled degradation profiles over six to nine months. Commercial availability in Germany, Austria, and the Czech Republic followed in Q1 2026, with broader European distribution planned through 2025.
| ATTRIBUTES | DETAILS |
|---|---|
|
Market Size (Current)
Current market valuation
|
USD ($) 915.4 USD Million in 2026 |
|
Market Size (Forecast)
Projected market valuation
|
USD ($) 2,052.8 USD Million in 2036 |
|
Growth Rate
Compound Annual Growth Rate
|
CAGR of 8.4% from 2027 to 2036 |
|
Forecast Period
Analysis timeline
|
2026 - 2035 |
|
Base Year
Reference year for analysis
|
2026 |
|
Historical Data Available
Past market data availability
|
2022 - 2024 |
|
Regional Scope
Geographical coverage
|
Global |
|
Segments Covered
Market segments analyzed
|
Detailed segmentation covered in the report. |
Frequently Asked Questions
Common questions about this market report.
About the Author

Market Business Insights
No biography available for this author.
Detailed Table of Contents
Biliary Stents Market Segmentation
The global Biliary Stents Market is segmented based on the following categories, providing a detailed breakdown for comprehensive analysis:
| Segment Category | Segment Values |
|---|---|
| Detailed segmentation covered in the report. | |
Research Methodology
Our research methodology is carefully designed to deliver the clients with the most accurate, relevant, and actionable market insights to enable clear decision-making and leveraging of opportunities in the markets. We believe consistency, depth in analysis, and a tailored approach in each report are what help set us apart in the industry. The research methodology is based on an integrating research process consisting of in-depth data collection, a complex analysis, and a stringent validation system.
Data Collection
Data collection forms the basis of our study and gathers diverse authentic data to build the basis for deeper study in terms of market trends, competitive landscape, and growth prospects for Biliary Stents Market. Data collection takes place through two channels of main activities as follows:
Primary Data Collection
Primary data collection allows collecting real-time and firsthand information from market participants. This is an engagement process conducted by our team with other industry stakeholders, where a much deeper insight than any published data is pursued. This process includes:
- Direct Interviews – We interview the key decision-makers such as CEOs, product managers, innovation heads, and marketing directors to gather both qualitative and quantitative information. The questionnaire covers emerging trends, customer preferences, regulatory impact, and competitors’ strategies.
- Demand and Supply-Side Inputs – Interviews and surveys with supply and demand-side stakeholders provide a balanced view of prevailing market conditions, including feedback from manufacturers, distributors, suppliers, and end-users.
- Expert Opinions – Consultations with industry experts and domain specialists provide insights into future market direction, risks, and opportunities.
- Focus Groups and Online Surveys – Focus groups and surveys are used to understand consumer preferences and adoption probability of new products or services.
Primary research forms the core of our data validation process by offering direct insights into the market, addressing limitations in secondary data, and allowing for an adaptable research process.
Secondary Data Collection
Secondary research serves as a robust foundation for understanding market context, historical data, and larger trends. It involves systematic gathering of existing information from verified sources.
- Industry Reports and Publications – Market reports, white papers, and case studies from credible sources provide a broad view of the market landscape and key players.
- Government and Public Records – Data from government agencies and regulatory bodies helps analyze economic factors and policy impacts.
- News and Media Outlets – Monitoring news articles, press releases, and media reports keeps us updated on market developments and M&A activity.
- Proprietary and Paid Databases – Databases such as Bloomberg, Factiva, D&B Hoovers, and Thomson Reuters provide validated and cross-referenced data.
- Financial Reports and SEC Filings – Financial statements, annual reports, and investor presentations provide insights into revenue structures and profitability.
This combination of primary and secondary data sources enables us to provide a comprehensive view of the Biliary Stents Market, supported by authenticated information across multiple sources.
Data Analysis Techniques
With the data collected, we initiate a rigorous analysis phase. We analyze market dynamics, growth patterns, and future performance using analytical models and statistical tools.
Top-Down and Bottom-Up Market Sizing Approaches
- Top-Down Approach – Starts with global market size and distributes it across segments using macro-level trends and established proportions.
- Bottom-Up Approach – Aggregates company-level and country-level revenue data to build regional and global market estimates.
These two approaches are cross-validated to remove inconsistencies and ensure accurate market estimation.
Forecasting Models and Market Dynamics Analysis
- Time-Series Analysis – Models historical trends, seasonality, and demand cycles.
- Econometric and Judgmental Forecasting – Combines economic models with expert-driven adjustments.
- Delphi Method – Uses iterative expert input to generate balanced market forecasts.
Data Triangulation and Validation
- Multi-source cross-verification of all data points
- Use of quantitative and qualitative validation techniques
- Sample validation through expert and stakeholder feedback
Market Analysis and Sizing Estimation
- Detailed segmentation analysis
- Competitive landscape evaluation
- Revenue modeling using TAM, SAM, and SOM frameworks
Quality Assurance and Final Review
- Data accuracy and consistency checks
- Content, language, and structure review
- Client-specific customization and refinement
Continuous Improvement in Methodology
We continuously refine our research methodologies based on evolving market conditions, client feedback, and technological advancements. This ensures our research remains accurate, relevant, and aligned with industry standards.













